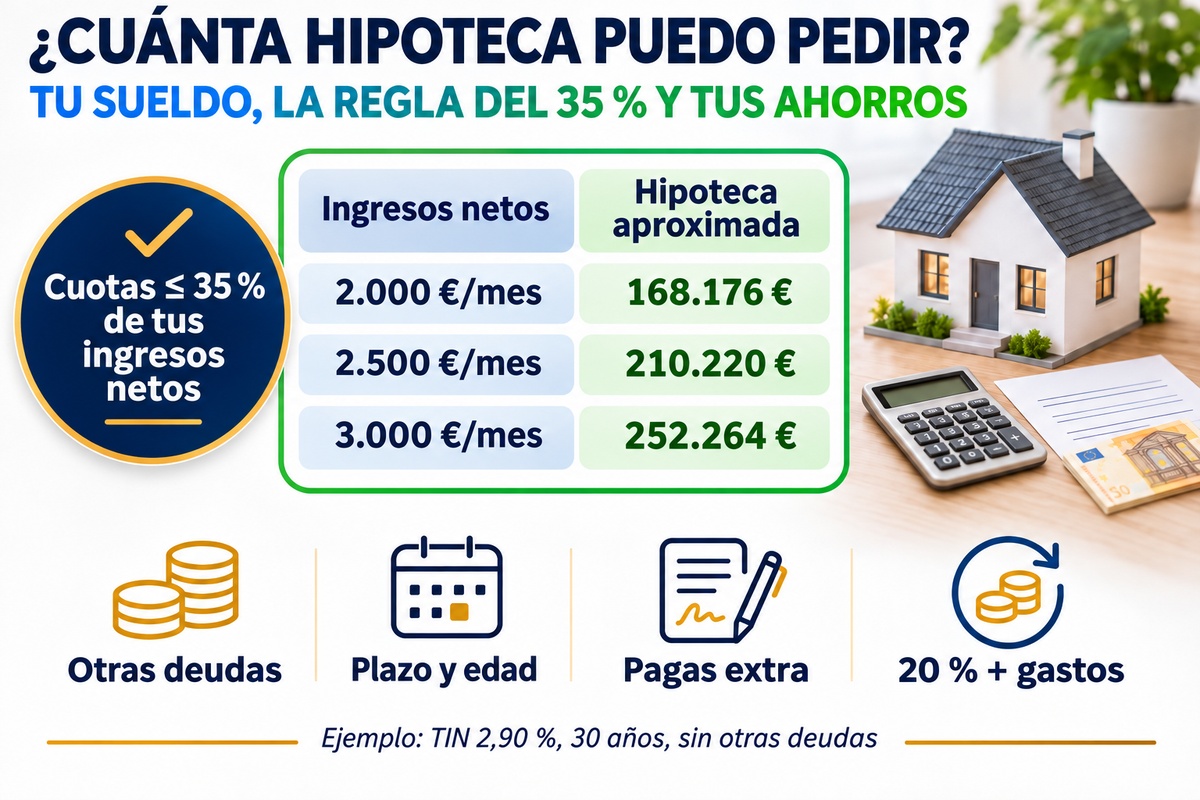
It is the first question almost every buyer asks. The answer does not depend only on your salary, but on three figures: how much you earn, how much you already owe and how much you have saved. With them, the bank's calculation is fairly predictable.
The rule banks use
The Bank of Spain points out that lenders usually consider that the sum of your repayments, mortgage included, should not exceed 30-35% of your net income. It is not a law but a risk criterion, and each lender applies it in its own way.
From that maximum repayment, the loan amount depends on the interest rate and the term. And there is a second limit: banks usually finance at most 80% of the price or of the valuation (tasación), whichever is lower.
Table: how much you can borrow according to your income
| Household net monthly income | Maximum repayment (35%) | Approximate mortgage (30 years) | Approximate property price | Approximate savings needed |
|---|---|---|---|---|
| Household net monthly income€1,500 | Maximum repayment (35%)€525 | Approximate mortgage (30 years)€126,132 | Approximate property price€157,665 | Approximate savings needed€47,300 |
| Household net monthly income€2,000 | Maximum repayment (35%)€700 | Approximate mortgage (30 years)€168,176 | Approximate property price€210,220 | Approximate savings needed€63,066 |
| Household net monthly income€2,500 | Maximum repayment (35%)€875 | Approximate mortgage (30 years)€210,220 | Approximate property price€262,775 | Approximate savings needed€78,833 |
| Household net monthly income€3,000 | Maximum repayment (35%)€1,050 | Approximate mortgage (30 years)€252,264 | Approximate property price€315,330 | Approximate savings needed€94,599 |
| Household net monthly income€3,500 | Maximum repayment (35%)€1,225 | Approximate mortgage (30 years)€294,308 | Approximate property price€367,886 | Approximate savings needed€110,366 |
| Household net monthly income€4,000 | Maximum repayment (35%)€1,400 | Approximate mortgage (30 years)€336,353 | Approximate property price€420,441 | Approximate savings needed€126,132 |
Illustrative calculation: nominal rate (TIN) of 2.90%, 30 years, maximum repayment of 35% and no other debts. The property price assumes 80% financing. The savings needed include the 20% down payment and around 10% in purchase costs; depending on your region it may be more or less. Each bank applies its own criteria.
What changes the result
- Your other debts. Every repayment you already make is deducted from the maximum repayment. With €2,500 net and a €200 monthly car loan, the available repayment drops from €875 to €675 and the maximum mortgage from about €210,220 to about €162,170.
- The interest rate. With €2,500 net, going from a nominal rate of 2.90% to 3.90% reduces the maximum mortgage to about €185,512: €24,709 less.
- The term. The more years, the lower the repayment and the higher your capacity, but also the more interest. Many banks cap the age at which the loan must be repaid, usually between 75 and 80.
- Extra payments. If you are paid 14 times a year, the bank usually spreads the extra payments over the year: €1,800 × 14 / 12 = €2,100 a month.
- Two borrowers. Both incomes are added together, and so are both sets of debts.
- The type of contract. A permanent contract with seniority carries more weight than other profiles. We explain it in our guides on mortgages for the self-employed and with a temporary contract.
The other limit: your savings
Even if your income would allow more, the bank usually finances up to 80%. The rest, plus the purchase taxes and costs, comes out of your savings: as a guide, around 30% of the price. You will find the breakdown by region in our article on how much money you need to buy. If you meet its requirements, the Aval ICO can help you finance more of your first home.
How to work out your figure in three steps
- Add up your net monthly income, and the co-borrower's if there is one.
- Multiply by 0.35 and subtract the repayments on the loans you already have.
- With that repayment, calculate the amount with our simulator, or ask for an assessment to find out what the bank would actually approve.
The Duplo Capital advantage
A table gives you an idea. An assessment of your case gives you a figure to start house-hunting with.
Frequently asked questions about how much mortgage you can get
With a maximum repayment of 35% (€700), a nominal rate of 2.90% and 30 years, about €168,000, with no other debts. For a property of about €210,000 you would also need around €63,000 in savings.
No. It is a risk criterion used by banks: the Bank of Spain points out that lenders usually set it at 30-35% of net income, including other debts.
Yes. The bank usually spreads them over 12 months.
Yes: the repayment goes down and your capacity goes up, but you will pay more interest. The term also depends on your age.
Some lenders do so for solid profiles, and the Aval ICO can help you with your first home if you meet its requirements.
Yes, if they are a co-borrower. Their income is added, but so are their debts, and you are both liable for the whole mortgage.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT