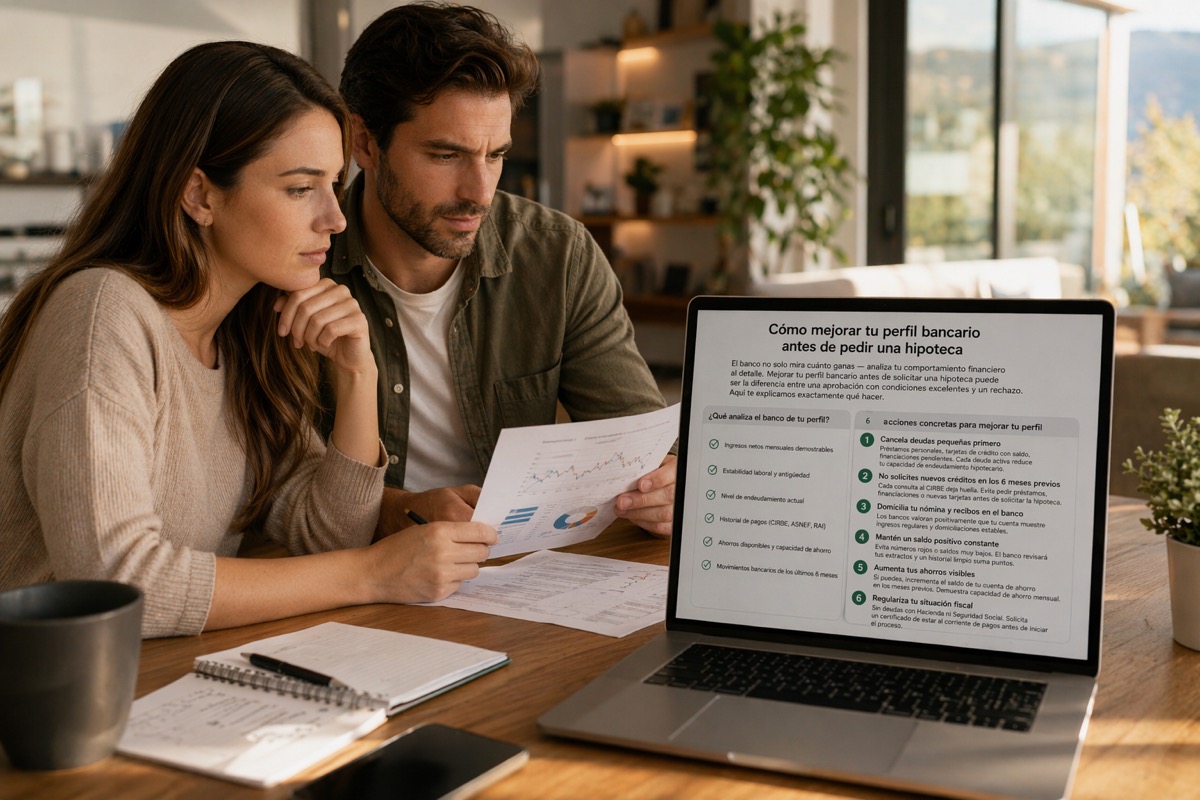
The bank doesn't just look at how much you earn — it analyzes your financial behavior in detail. Improving your bank profile before applying for a mortgage can be the difference between approval with excellent conditions and rejection. Here we explain exactly what to do.
What does the bank analyze about your profile?
- Demonstrable net monthly income
- Job stability and seniority
- Current debt level
- Payment history (CIRBE, ASNEF, RAI)
- Available savings and saving capacity
- Bank movements for the last 6 months
6 concrete actions to improve your profile
1. Cancel small debts first
Personal loans, credit cards with balances, pending financing. Each active debt reduces your mortgage borrowing capacity.
2. Don't apply for new credit in the 6 months prior
Each CIRBE query leaves a trace. Avoid requesting loans, financing or new cards before applying for a mortgage.
3. Direct deposit your salary and bills at the bank
Banks value positively that your account shows regular income and stable direct debits.
4. Keep a constant positive balance
Avoid overdrafts or very low balances. The bank will review your statements and a clean history adds points.
5. Increase your visible savings
If you can, increase your savings account balance in the months before. Demonstrate monthly saving capacity.
6. Regularize your tax situation
No debts with the tax office or Social Security. Request a certificate of being up to date with payments before starting the process.
How much time do you need to improve your profile?
- 1 month: Cancel small debts and cards
- 3 months: Stabilize bank movements
- 6 months: Optimized profile to apply for a mortgage
Want to know if your profile is financeable today?
Request your free analysis and we'll tell you exactly what to improve.
FREE PROFILE ANALYSIS