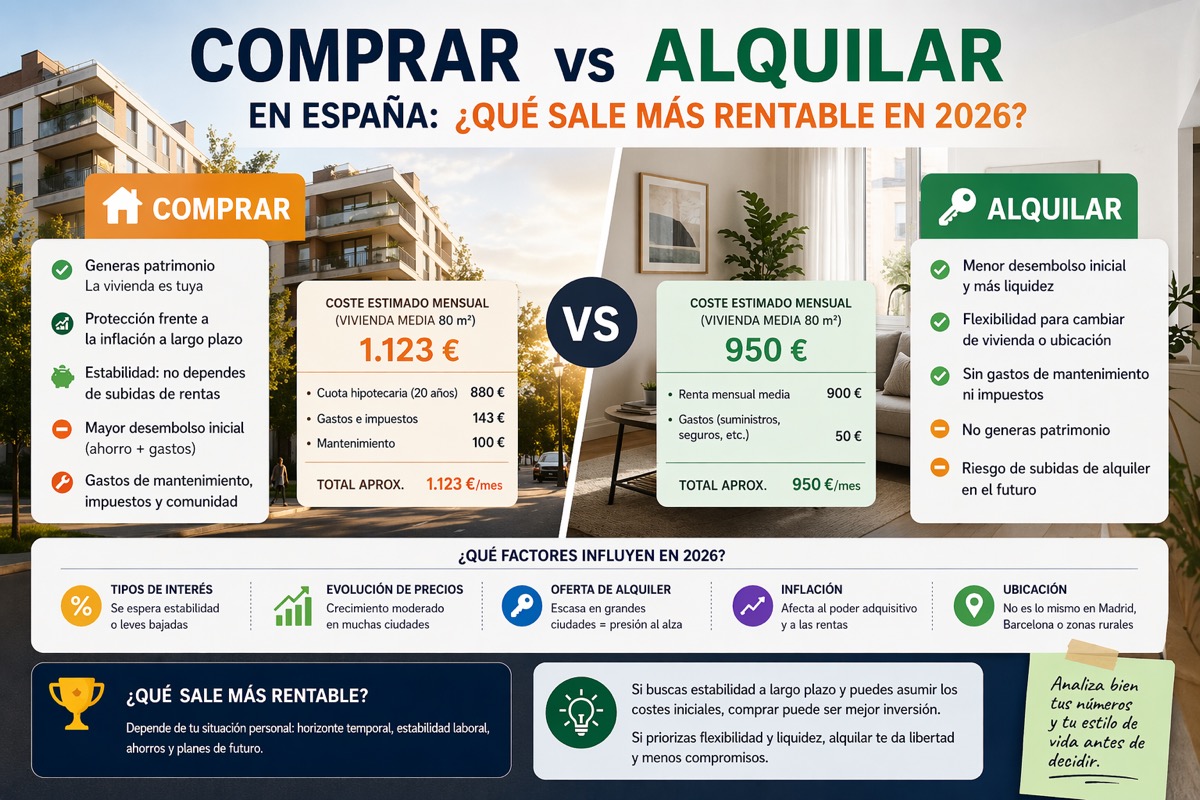
The eternal question of the Spanish real estate market has a clearer answer than ever in 2026. With rents at historic highs in major cities and mortgage rates moderating, the financial analysis increasingly favors buying for those who can access financing.
The market situation in 2026
- Rents in Barcelona and Madrid: historic highs
- Purchase prices: moderate growth compared to 2023-2024
- Mortgage rates: in the process of moderating
- Rental supply: historic lows due to reduced stock
The real calculation — Buying vs renting
| Buy | Rent | |
|---|---|---|
| Monthly payment / rent | ~€948 (€200K mortgage, 25 years, 3%) | ~€1,200 (Barcelona/Madrid) |
| Upfront costs | ~€40,000 (deposit + costs) | ~€2,400 (security deposit + agency) |
| After 25 years | Home paid off + equity | €0 in equity generated |
| Monthly difference | -€252 by buying, plus property ownership | |
When is it better to rent?
- If your work or personal situation is unstable
- If you plan to change cities in less than 3 years
- If you don't have enough savings for the down payment
- If the purchase price in your area is disproportionate compared to rent
When is it better to buy?
- If you've been in the same city for more than 2 years
- If you have job stability and sufficient savings
- If the equivalent rent exceeds your mortgage payment
- If you want to build long-term wealth
Duplo Capital's conclusion
In most cases analyzed in 2026, for profiles with job stability and sufficient savings, buying becomes more profitable from year 4-5. The break-even point depends on the city, purchase price and mortgage conditions obtained.
Can you afford to buy in 2026?
Calculate your mortgage capacity and discover what you can finance.
CALCULATE YOUR MORTGAGE CAPACITY