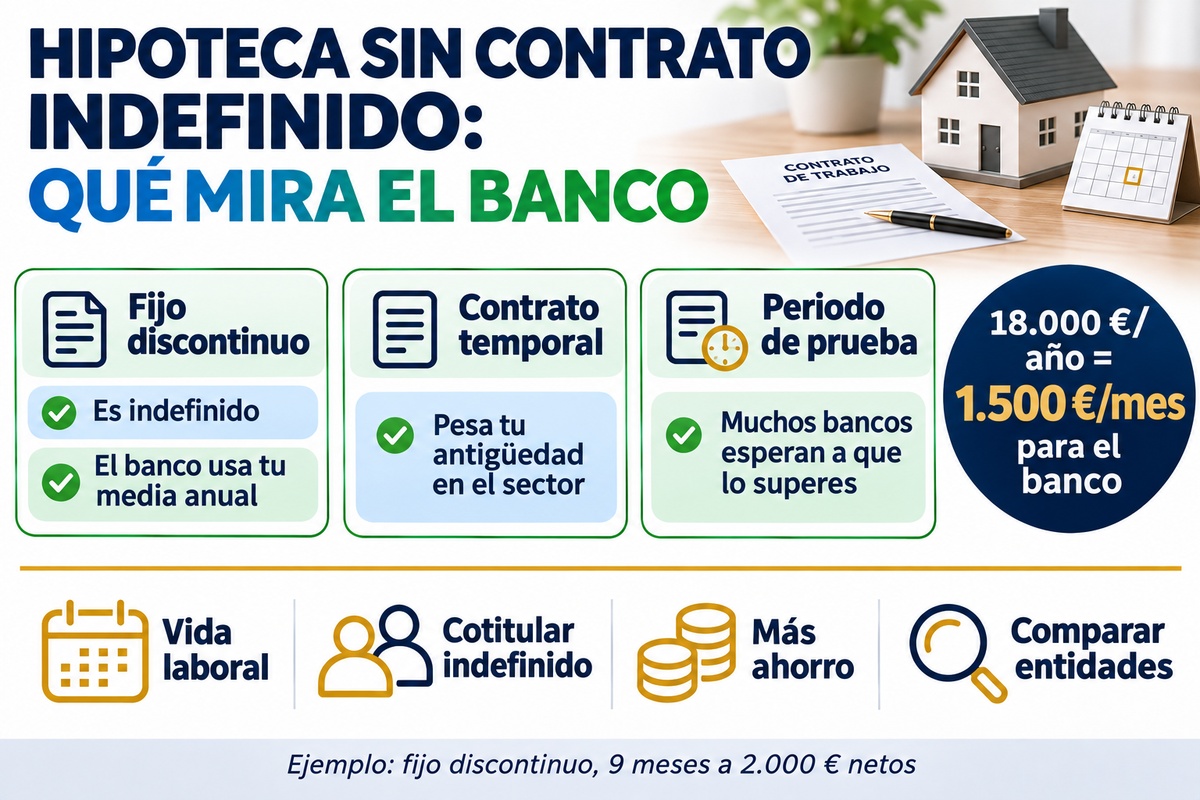
A permanent contract makes getting a mortgage much easier, but it is not a legal requirement. With a temporary contract, a seasonal permanent contract (fijo discontinuo) or as a recent hire, it can also be done. However, the bank will ask for more proof that your income will keep coming in.
Why the contract matters so much
A mortgage is repaid over 25 or 30 years. That is why the bank looks not only at how much you earn today, but at how likely you are to keep earning it. Spain's Law 5/2019 requires it to assess your creditworthiness taking into account, among other factors, your employment situation and your current and foreseeable income. A permanent contract with seniority is the clearest signal; other contracts need support.
Fijo discontinuo: it is permanent, but the bank looks at your annual income
The fijo discontinuo is an open-ended contract for seasonal work or work that recurs intermittently (article 16 of the Workers' Statute, Estatuto de los Trabajadores). For the bank it is a better sign than a temporary contract, although not all lenders value it in the same way. What changes is the calculation: the bank usually takes your income over the whole year, not just the months you work.
An example: you work 9 months a year and earn €2,000 net in those months, that is, €18,000 a year or €1,500 a month on average. With a maximum repayment of 35% (€525), a nominal rate (TIN) of 2.90% and 30 years, the bank could lend you about €126,132. If it counted €2,000 a month, it would be about €168,176: a difference of €42,044.
Illustrative example with fictitious figures and no other debts. Each bank applies its own criteria.
To strengthen your file, provide your Social Security work history (vida laboral) and payslips from several seasons: they show that your work recurs year after year.
Temporary contract: your track record counts more than the contract
With a temporary contract it is harder, but not impossible. What banks value most:
- Your seniority in the same sector, even if you have changed employer.
- A co-borrower with a permanent contract, who brings stable income.
- More savings, so you borrow a smaller percentage of the price.
- A history without long periods out of work, with contracts that are renewed or follow on from each other.
- A guarantor, in some cases.
Probation period and a recent job change
Many banks prefer to wait until you have completed your probation period, and it is common for them to ask for 6 to 12 months' seniority in your current job. Each lender has its own criteria.
If you are already in the middle of the mortgage process, think carefully before changing jobs: moving to a temporary contract or going back into a probation period can hold up the transaction. If the change is for the better, for example to a permanent contract with a higher salary, let the bank know and provide the new contract.
How to strengthen your file
- A complete work history (vida laboral), contracts and payslips from recent years.
- Bank statements showing regular income and the ability to save.
- A co-borrower or a guarantor, if your profile needs one.
- Fewer debts: every repayment you eliminate adds capacity. Here is how to improve your bank profile.
- Several lenders: not all of them value these contracts in the same way, so it pays to compare.
- A realistic budget: first work out how much you can borrow on your salary.
The Duplo Capital advantage
With a less stable contract, choosing the right lender makes all the difference.
Frequently asked questions about mortgages without a permanent contract
Yes, although it is harder. Seniority in the sector, a co-borrower with a permanent contract, more savings or a guarantor all help.
Yes. It is an open-ended contract under article 16 of the Workers' Statute (Estatuto de los Trabajadores). The bank usually calculates your income using the yearly average.
Some lenders accept it, but many prefer to wait until you have completed it. Each bank has its own criteria.
It is common for them to ask for 6 to 12 months in your current job, although it depends on the bank and the rest of your profile.
Let the bank know. Moving to a temporary contract or a probation period can hold up approval; a move to a permanent contract with a higher salary usually improves your profile.
It can help in some cases, but the guarantor is liable for the debt with their own assets. Banks often prefer a second borrower.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT