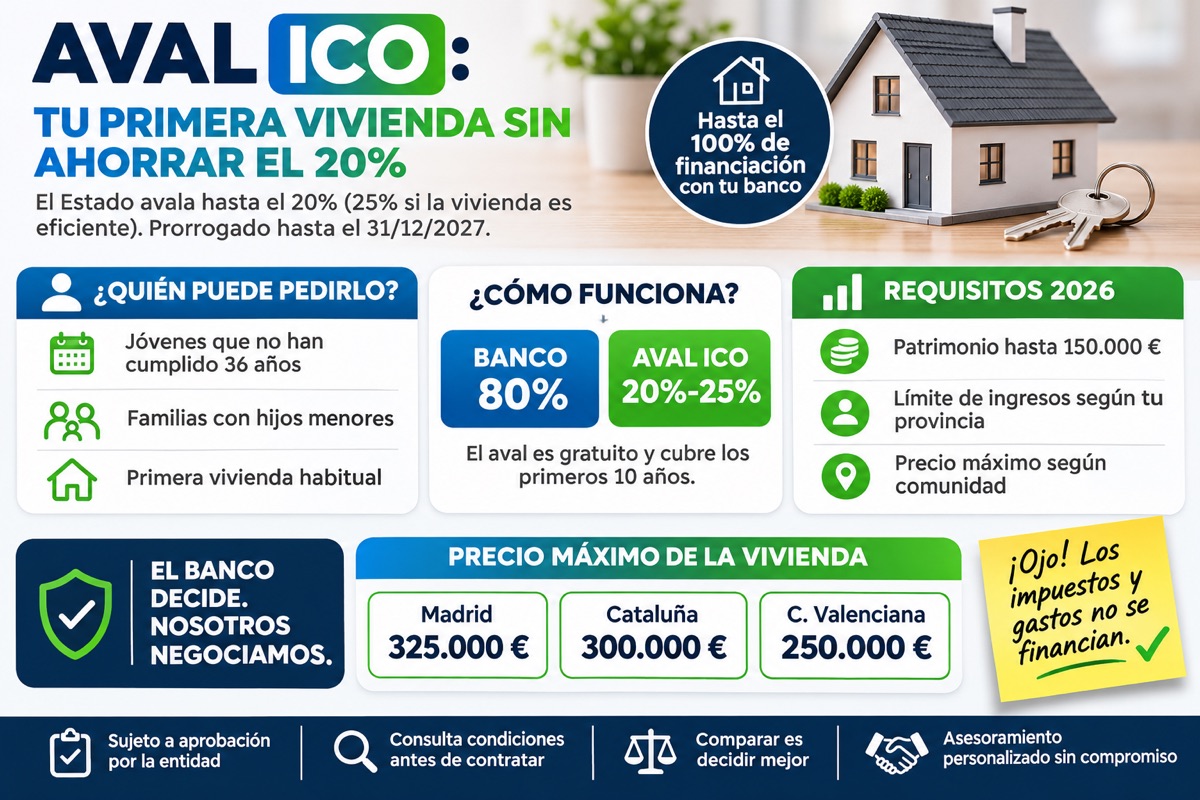
The Aval ICO is the public support scheme that lets young people and families with children buy their first home without having saved the 20% deposit. In 2026 the Government extended it until the end of 2027 and widened the requirements so it reaches more buyers. We explain how it works and what to bear in mind before signing.
What is the Aval ICO?
Banks usually finance at most 80% of a property's value. The remaining 20%, plus taxes and costs, has to come from your savings. The guarantee line for buying a first home (Línea de Avales para la adquisición de primera vivienda), managed by the Instituto de Crédito Oficial (ICO) on behalf of the Ministry of Housing, covers exactly that part: the State guarantees up to 20% of the loan to the bank, or up to 25% if the property has an energy rating of D or better.
Important: the ICO does not lend you money. You sign a single mortgage with the bank, which can reach 100% of the purchase price or the valuation (whichever is lower), and the guarantee covers the bank for the part that goes beyond the usual amount. The guarantee is free for the buyer and covers the first 10 years of the loan.
Aval ICO requirements in 2026
Following the addendum published in the BOE on 2 July 2026, the conditions are as follows:
- Age or dependent children — Young people who have not turned 36 on the signing date, or families with at least one dependent minor (in this case, with no age limit).
- Income — Since 19 June 2026 the limit depends on the province where you buy. The general limit is still 4.5 times the IPREM (€37,800 gross a year per buyer); it rises to 5.5 times (about €46,200) in provinces such as Valencia, Alicante or Zaragoza and to 7.5 times (about €63,000) in Barcelona, Girona, Madrid, Málaga or the Balearic Islands. If two of you are buying, each person's limits are added together. Families add 0.3 times the IPREM for each minor, and single-parent families can raise the limit by 70%.
- Assets — Up to €150,000 per buyer (previously €100,000).
- First home — Not having owned another home, with some exceptions (an inherited share, a home that is unavailable after separation or divorce, etc.).
- Residence — Legal residence in Spain during the two years before the application. A maximum of two buyers.
- No defaults — Not being listed as a defaulter in the Bank of Spain's CIRBE.
- The property — New or resale, already built, for habitual and permanent residence, and with a price that does not exceed the maximum for its autonomous community.
Maximum property price by autonomous community
The purchase price cannot exceed a limit that varies by region. Some examples:
- Community of Madrid — €325,000
- Catalonia, the Basque Country and Navarre — €300,000
- Aragon and Illes Balears — €275,000
- Comunitat Valenciana, Galicia, Murcia and most regions — €250,000
- Andalusia — €225,000
- Extremadura — €200,000
In areas such as Barcelona or central Madrid, this limit rules out a large part of what is on the market. That is why it is worth defining your search area with your real budget before you start viewing flats.
What the Aval ICO does not cover
- Taxes and purchase costs — The guarantee lets you finance the price, not the ITP or IVA, the notary, the land registry or the valuation. As a guide, in Catalonia, with a general ITP of 10%, it is wise to have around 11-12% of the price saved.
- The bank's decision — Meeting the requirements does not guarantee the mortgage. Each lender assesses your creditworthiness and sets the interest rate and terms.
- The total cost — By financing more, you pay interest on a larger amount. You need to compare the monthly payment and the total cost, not just the financing percentage.
- Other support schemes — The guarantee is not compatible with other public guarantees. In Catalonia, for example, you have to choose between the Aval ICO and the ICF's Préstecs Emancipació.
How to apply
You do not apply for the guarantee to the ICO but to the bank. You need to go to a lender that has signed up to the scheme, which will ask for the usual mortgage paperwork plus a negative cadastral certificate or a land registry extract (nota simple) proving you do not own another home, your latest income tax return, the energy performance certificate and the valuation. The deadline for signing loans with the guarantee is 31 December 2027.
The Duplo Capital advantage
Duplo Capital checks whether you meet the Aval ICO requirements before you start negotiating and presents your application to the participating banks that best suit your profile.
Frequently asked questions about the Aval ICO
It is open to young people who have not turned 36 when signing the mortgage and to families with dependent minor children, with no age limit. You must also be buying your first habitual home, never have owned another, have had legal residence in Spain for at least two years, have assets of up to €150,000 and not exceed the income limit of the province where you are buying.
Until 18 June 2026 the limit was €37,800 gross a year per buyer (4.5 times the IPREM) throughout Spain. Since 19 June it depends on the province: it stays at 4.5 times in most of them, rises to 5.5 times (about €46,200) in provinces such as Valencia or Alicante and to 7.5 times (about €63,000) in Barcelona, Madrid or Málaga. If two people are buying, their limits are added together. Families with minors have a higher limit for each child, and single-parent families can raise it by 70%.
It allows the bank to finance up to 100% of the lower of the purchase price and the valuation. But it does not cover taxes or purchase costs, which you have to pay from your savings. In addition, the bank decides whether to grant the mortgage and on what terms.
The deadline for signing loans with this guarantee has been extended to 31 December 2027, according to the addendum to the agreement between the Ministry of Housing and the ICO published in the BOE on 2 July 2026.
The guarantee is free for the buyer. What does change is the mortgage: by financing a higher percentage, you pay interest on more capital. That is why it is worth comparing the monthly payment and the total cost of several offers before deciding.
The guarantee is not compatible with other public guarantees. It is compatible with your autonomous community's tax benefits, such as the reduced ITP for young buyers. In Catalonia, for example, you will have to choose between the Aval ICO and the ICF's Préstec Emancipació.
Do you meet the Aval ICO requirements?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT