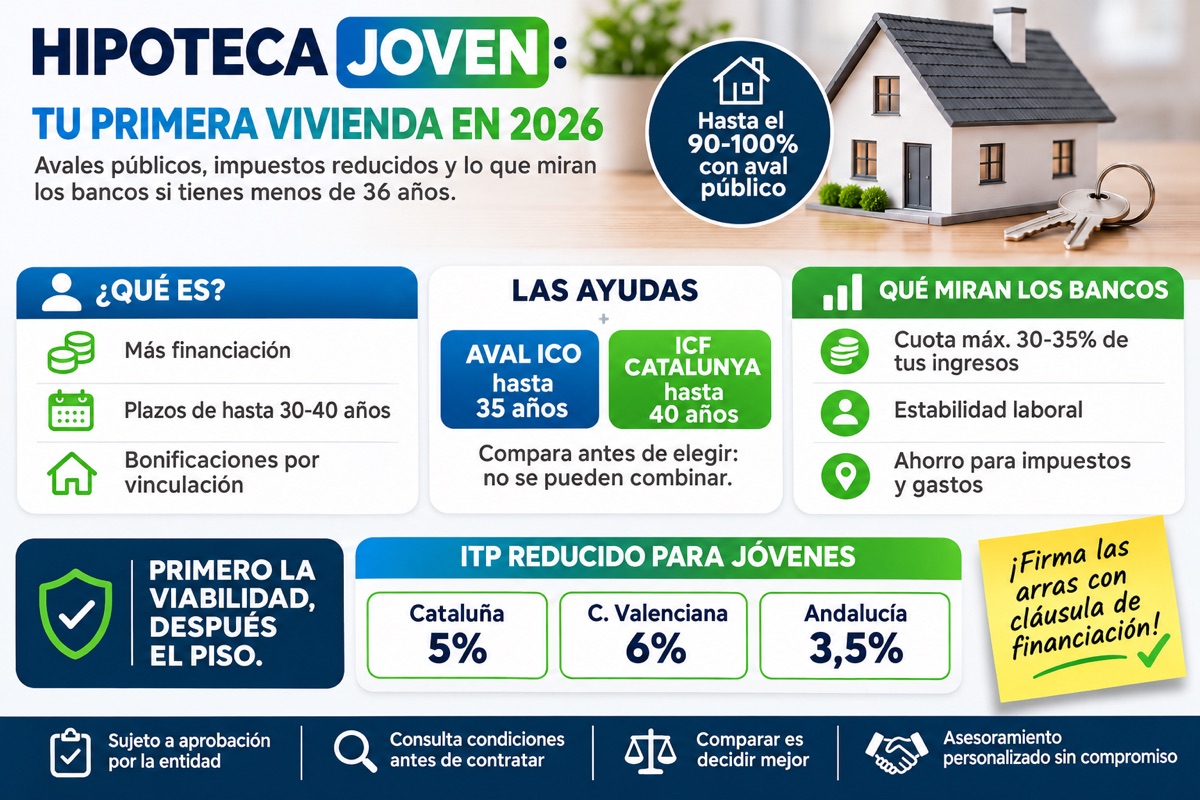
Most young people looking for a home do not have a salary problem but a savings problem: putting together the deposit and the taxes takes years. The good news is that in 2026 there are more tools than ever to buy sooner. We explain what a young buyer mortgage is, what support exists and what banks look at.
What is a young buyer mortgage?
It is not an official product. It is the name banks give to mortgages designed for people under 35 or 36, which usually combine three things:
- More financing — Up to 90-100% of the property's value, almost always backed by a public guarantee.
- Long terms — Up to 30 or even 40 years, to reduce the monthly payment. Many banks require the loan to end before a certain age.
- Welcome terms — Interest rate discounts in exchange for paying your salary into the bank or taking out other products.
The support schemes that make it possible
- State Aval ICO — For young people who have not turned 36 when signing. The State guarantees up to 20% of the loan (25% if the property is energy-efficient), making it possible to finance up to 100%. Extended until 31 December 2027.
- Préstec Emancipació in Catalonia — The ICF lends up to 20% of the price, with a maximum of €50,000, at 0%. Now up to age 40.
- Regional guarantees — Other regions have their own programmes, such as Mi Primera Vivienda in the Community of Madrid or the guarantees from the Institut Valencià de Finances in the Comunitat Valenciana.
Reduced ITP for young buyers by region
If you buy a resale property you pay Property Transfer Tax (ITP), which each region sets. Many have a reduced rate for young buyers:
- Catalonia — 5% instead of the general 10%, up to age 35, for a habitual residence and with an IRPF taxable base of up to €36,000.
- Comunitat Valenciana — 6% for under-35s if the property does not exceed €180,000 (8% if it does), compared with the general 9% since June 2026. With income limits.
- Andalusia — 3.5% for under-35s if the property does not exceed €150,000, compared with the general 7%.
Each region has its own price and income limits, and they change frequently. Check them before working out your budget.
What banks look at
- Debt-to-income ratio — The monthly payment should not exceed 30-35% of your net monthly income.
- Job stability — A permanent contract past the probation period, or at least two years of activity if you are self-employed.
- Savings for costs — Even if 100% of the price is financed, you have to pay taxes and costs from your savings.
- Clean credit history — No defaults or high debts: consumer loans, cards or car finance reduce your borrowing capacity.
Common mistakes when applying for a young buyer mortgage
- Looking for a home before knowing how much you can borrow — Start with the viability study.
- Forgetting the costs — ITP or IVA, the notary and the land registry are not financed.
- Looking only at the interest rate — Compare the TAE (APR) and the cost of linked products.
- Signing the deposit contract (arras) without a financing clause — If the mortgage falls through, you could lose your deposit.
- Not checking the limits of the support schemes — Age, income and maximum price decide whether you can use them.
The Duplo Capital advantage
Duplo Capital analyses your profile, combines the support you are entitled to and negotiates with more than 20 banks to get your first mortgage on the best terms.
Frequently asked questions about young buyer mortgages
It is the name banks give to mortgages aimed at people under 35 or 36. They usually offer more financing, normally backed by a public guarantee, long terms and interest rate discounts. It is not an official product, so the terms vary from one bank to another.
It depends on the scheme or the bank. The Aval ICO requires you not to have turned 36 when signing, the reduced ITP usually applies up to age 35 and Catalonia's Préstec Emancipació now goes up to 40.
Yes, especially with the Aval ICO or a regional guarantee, which allow the bank to finance up to 100% of the price or the valuation. Even so, you will need savings to pay the taxes and purchase costs, and the bank will have to approve your creditworthiness.
With 100% financing, at least the taxes and costs of the purchase. On a resale property, ITP ranges from 3.5% to 10% depending on the region and your situation, plus notary, land registry and valuation. With an 80% mortgage you will also need 20% of the price.
Banks usually require the monthly payment not to exceed 30-35% of net monthly income. For example, for a monthly payment of €700, you would need a household net income of at least €2,000 a month. The viability study tells you exactly how much you can borrow.
Yes, and it usually helps because both incomes are added together. For the support schemes, both buyers have to meet the requirements. With the Aval ICO, for example, neither of you can have turned 36, and your income limits are added together.
Could you buy your first home this year?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT