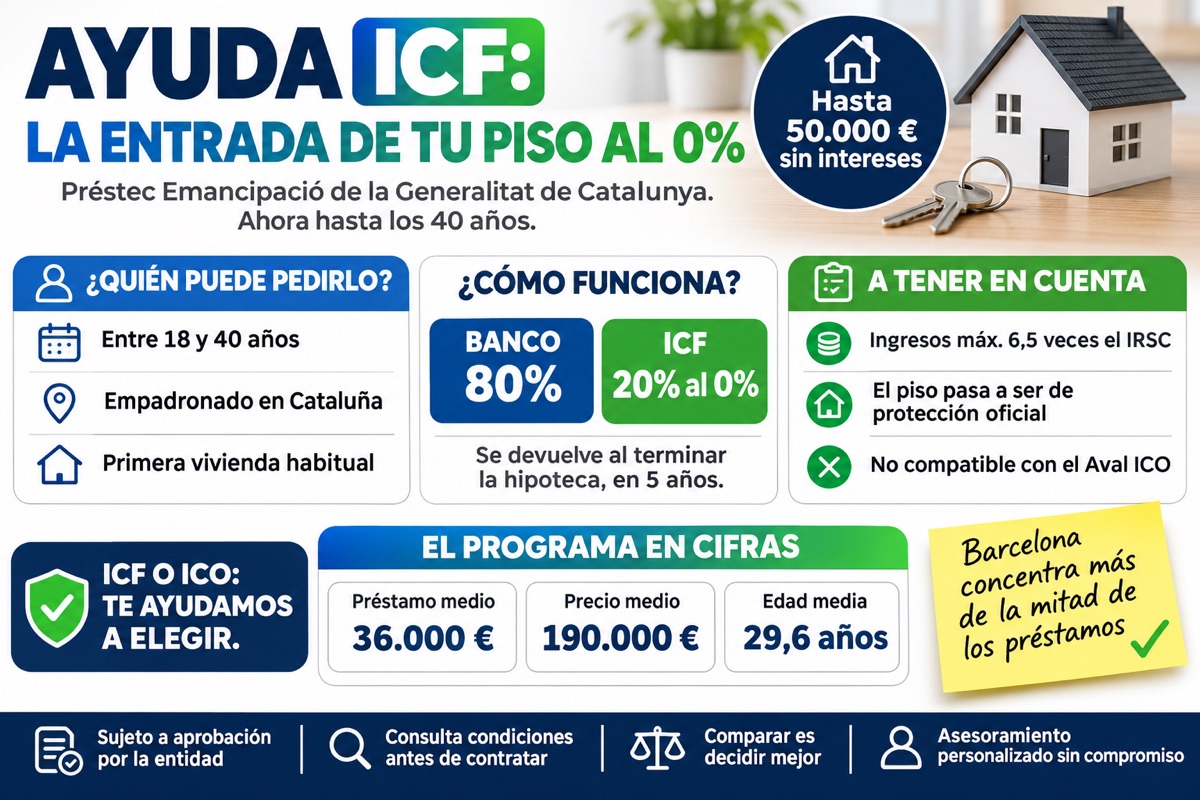
In Catalonia, people who can afford a mortgage but have not saved the deposit have a scheme of their own: the Préstecs Emancipació from the Institut Català de Finances (ICF). It is an interest-free loan that covers up to 20% of the property price and, since June 2026, is open to people aged up to 40.
What is the ICF's Préstec Emancipació?
It is a public loan from the Generalitat, managed by the ICF with funds from the Agència de l'Habitatge de Catalunya, designed to cover the deposit on your first home. It works in two parts:
- The bank — Finances up to 80% of the property's value with a standard mortgage.
- The ICF — Lends up to the remaining 20%, with a maximum of €50,000, at 0% interest and with no fees.
The most interesting part is repayment: you do not start repaying the ICF loan until you have finished paying off the mortgage. From then on you have five years to repay it, also interest-free.
Requirements in 2026
- Age — Between 18 and 40. The limit was 35 until 1 June 2026.
- Registration — Being registered as a resident (empadronado) in Catalonia.
- First home — It must be the first home you buy and become your habitual residence.
- Income — Gross annual income cannot exceed 6.5 times the IRSC (Catalonia's sufficiency income indicator). In 2025 this was around €80,963 for one buyer and €83,467 for two.
- Creditworthiness — No defaults or significant debts. The ICF assesses each case.
- The property — Located in Catalonia, with a valid certificate of occupancy (cédula de habitabilidad) and not previously classified as officially protected housing. Since 2026 a parking space and storage room in the same building can also be financed.
What you should know before applying
- The home becomes officially protected housing — Homes bought with this support are permanently classified as officially protected housing. This limits the price and conditions of any future sale or rental. It is an important decision that needs weighing up beforehand.
- The mortgage still depends on the bank — You need to get the 80% approved by one of the lenders participating in the programme.
- Purchase costs are not included — Taxes, notary and land registry are paid separately.
- It is not compatible with the Aval ICO — The State guarantee cannot be added to other public guarantees, so you have to choose one of the two routes.
How to apply, step by step
- 1. Application to the ICF — Submitted online, on the ICF website.
- 2. ICF approval — The ICF assesses your creditworthiness and gives its approval.
- 3. 80% mortgage — With that approval, you negotiate the mortgage with a participating lender (including CaixaBank/imagin, Kutxabank, Laboral Kutxa, CaixaGuissona and UCI).
- 4. Signing — The mortgage and the Préstec Emancipació are signed before a notary.
According to figures published by the ICF in July 2026, the programme has already helped buy close to 1,400 homes, with an average loan of around €36,000 and an average price of around €190,000. The average age of beneficiaries is 29.6, and more than half of the loans are concentrated in the Barcelona area.
Other support for buying in Catalonia
- Reduced 5% ITP for young buyers — Buyers aged up to 35 pay 5% ITP instead of the general 10% if the home will be their habitual residence and their IRPF taxable base does not exceed €36,000.
- AJD relief on new builds — Young people aged up to 35 who buy their habitual home from a developer get 100% relief on Stamp Duty (Actos Jurídicos Documentados).
- State Aval ICO — An alternative to the Préstec Emancipació for people under 36 and families with children, with a maximum price of €300,000 in Catalonia.
The Duplo Capital advantage
From our office in Barcelona, Duplo Capital compares the Préstec Emancipació, the Aval ICO and 90-100% mortgages so you can choose the option that really suits you.
Frequently asked questions about ICF support
It is a loan from the Generalitat de Catalunya, managed by the Institut Català de Finances, that covers up to 20% of the price of your first home, with a maximum of €50,000, at 0% interest. The bank finances the remaining 80% with a mortgage. The ICF loan is not repaid until the mortgage is paid off, and then there are five years to repay it.
Since 1 June 2026, people aged between 18 and 40 who are registered as residents in Catalonia can apply. The limit used to be 35.
Gross annual income cannot exceed 6.5 times the IRSC. With 2025 values, that means around €80,963 for a single buyer and €83,467 for two. It is worth checking the updated figure on the ICF website before applying.
The ICF has an agreement with several participating lenders, including CaixaBank (through imagin), Kutxabank, Laboral Kutxa, CaixaGuissona and UCI. The list may change, so it is advisable to check it on the ICF website.
No. The Aval ICO is not compatible with other public guarantees, so you have to choose one route or the other. The main difference is that the ICF lends the deposit interest-free, while the ICO guarantees a larger mortgage with the bank.
Homes bought with a Préstec Emancipació permanently become officially protected housing. This means any future sale or rental will be subject to the price limits and conditions of protected housing. It is a key point to weigh up before applying for the support.
Can you buy with the Préstec Emancipació?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT