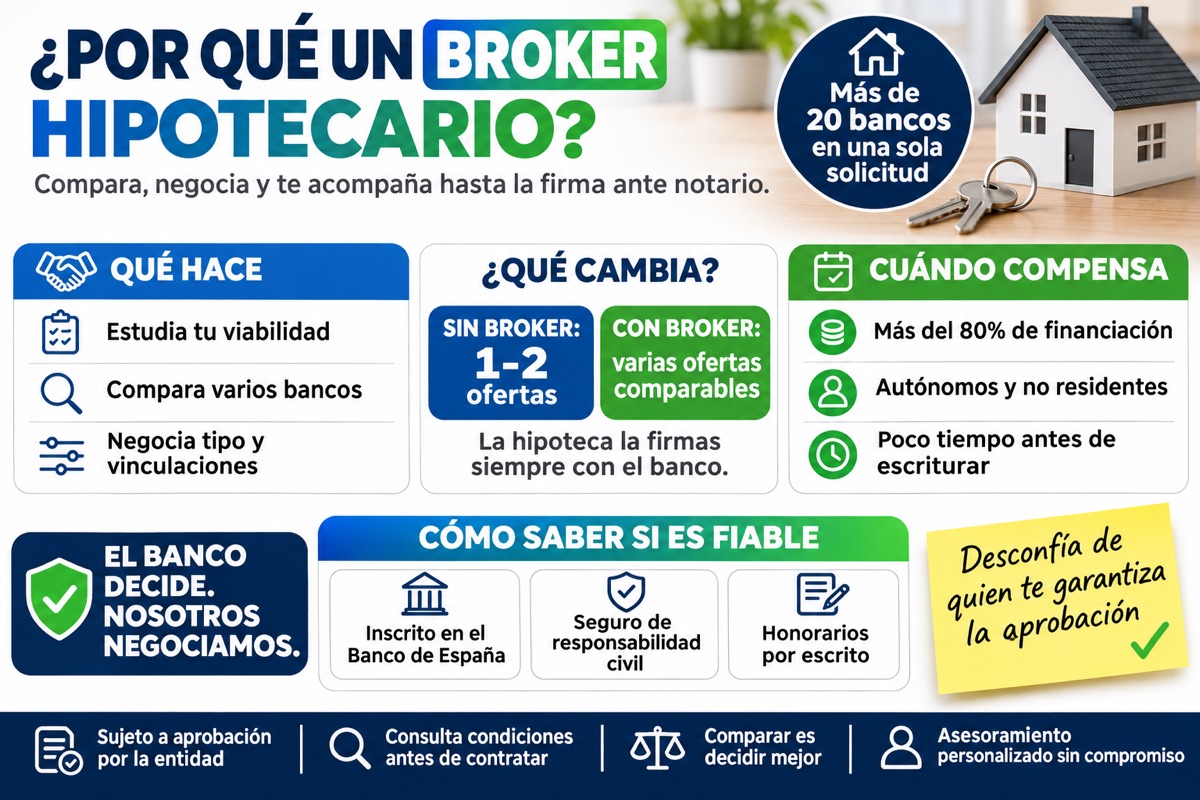
Applying for a mortgage bank by bank takes weeks and rarely lets you know whether the offer in front of you is the best possible one. A mortgage broker does that work for you: they compare, negotiate and support you all the way to signing. We explain exactly what they do, what protection the law gives you and when it pays off.
What does a mortgage broker do?
A mortgage broker, or real estate credit intermediary, is a professional who analyses your situation, presents your application to several lenders and negotiates the terms on your behalf. They do not lend the money: you always sign the mortgage with the bank. Their job is to make sure that mortgage is the one that best suits your profile.
In practice, a good broker:
- Assesses your viability — Works out how much you can borrow, with what monthly payment and what savings you need before you reserve a flat.
- Prepares your file — Organises your documents and presents your profile as strongly as possible.
- Compares several banks at once — Instead of one or two offers, you get several comparable proposals.
- Negotiates — Interest rate, margin, linked products (insurance, salary, cards) and fees.
- Supports you through to signing — Review of the FEIN, valuation, appointment with the notary.
What protection the law gives you
Since Ley 5/2019 on real estate credit, mortgage intermediation has been regulated. An intermediary must:
- Be registered in an official register — That of the Bank of Spain or of their autonomous community. The register is public and you can check it online.
- Have professional liability insurance — Or an equivalent bank guarantee, which protects the client against professional errors.
- Inform you in writing before starting — Who they are, which register they are listed in, whether they are tied to any lender and what their fees are.
- Respect the transparency periods — The bank gives you the FEIN and the other documents at least 10 days in advance, and the notary explains them to you free of charge in the transparency deed before signing.
Tied or non-tied intermediary
Not all intermediaries work the same way. A tied intermediary acts on behalf of one or several specific lenders and can only offer you their products. A non-tied one can present your application to different banks on the market. The law requires you to be informed of that tie in writing, and the term "independent advice" is reserved for a regulated service with additional requirements. Always ask how many lenders your broker works with and whether they are tied to any of them.
When it pays off (and when it doesn't)
A broker adds the most value when your case is not the simplest:
- You need more than 80% financing — Few lenders accept it and each has its own conditions.
- You are self-employed or have variable income — Knowing which bank best values your type of income avoids rejections.
- You are a non-resident or a foreign national — Policies vary a lot from one bank to another.
- You are short of time — For example, with a signed deposit contract (arras) and a deadline to complete.
- You want to improve your current mortgage — Subrogation, novation or switching banks.
If your profile is very strong, you need little financing and your bank already offers you excellent terms, you may not need one. Even then, comparing with at least one other offer is still a good idea.
There are no official statistics in Spain, but the sector's own estimates already put the share of mortgages signed with the help of an intermediary at around one in five.
How to tell whether a broker is reliable
- Check their registration number — On the Bank of Spain website or the regional register.
- Ask for the contract and fees in writing — Before starting, not at the end.
- Be wary of anyone who guarantees approval — The decision always lies with the bank.
- Read client reviews — And look at how they handled the difficult cases.
The Duplo Capital advantage
Duplo Capital is a mortgage broker registered with the Bank of Spain as a Real Estate Credit Intermediary (D568). We analyse your situation and negotiate with more than 20 banks to find the mortgage that best suits your profile.
Frequently asked questions about mortgage brokers
A real estate credit intermediary: a professional who analyses your profile, presents your application to several banks and negotiates the mortgage terms on your behalf. They do not lend the money; the mortgage is always signed with the bank. In Spain their activity is regulated by Ley 5/2019 on real estate credit.
Yes, as long as they are registered with the Bank of Spain or their autonomous community and have professional liability insurance or an equivalent guarantee, as required by Ley 5/2019. You can check their registration number online before signing anything.
In many cases yes, because they compare several lenders at once and know which bank best values each profile. But not always: if your bank already offers you excellent terms, the broker can confirm that it is the best option. What matters is comparing with real data.
It depends on the profile and the banks, but the initial study is usually quick. At Duplo Capital we give you a first answer on the viability of your purchase in under 48 hours. After that come the valuation, the bank's approval and the legal periods for the FEIN and the notary.
A tied intermediary acts on behalf of one or several specific lenders and can only offer their products. A non-tied one can present your application to different banks. The law requires you to be informed in writing of whether such a tie exists.
Yes. One bank saying no does not mean they all will, because each lender has its own risk criteria. A broker analyses the reason for the refusal, strengthens the file and presents it to the lenders where your profile fits best.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT