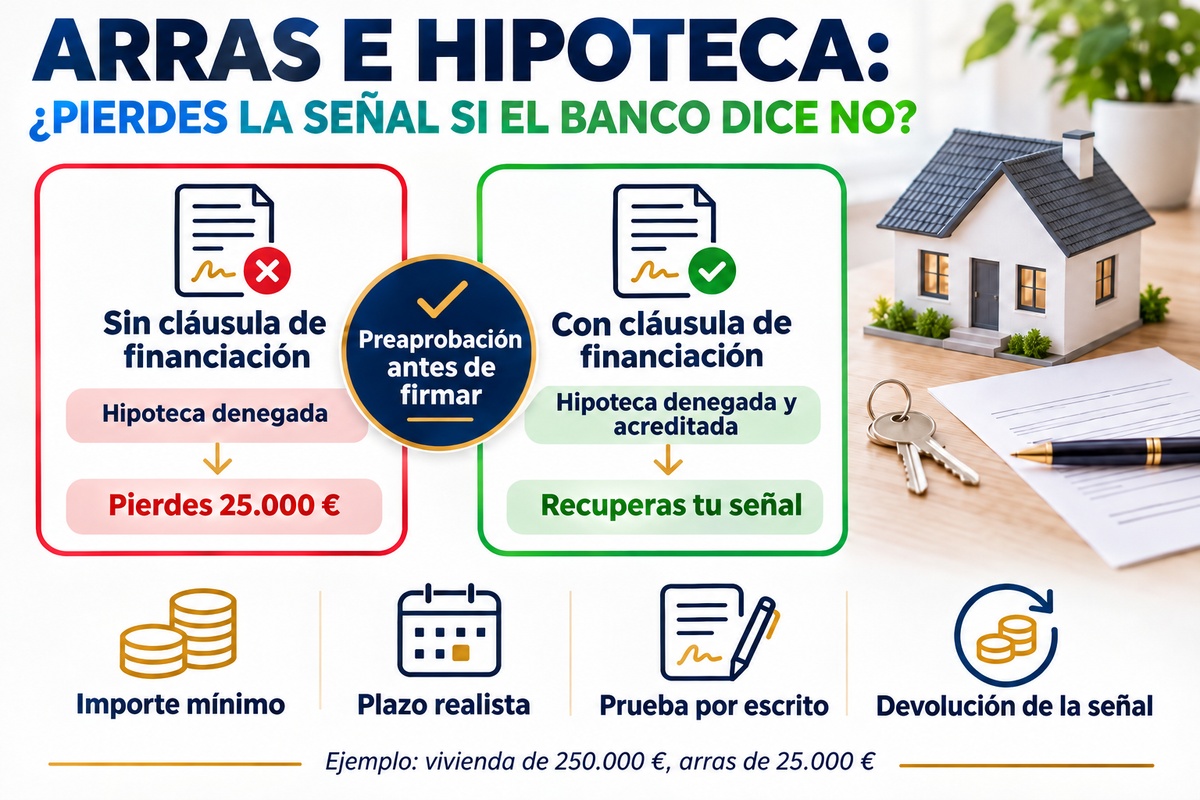
You have found the property, signed the deposit contract (arras) and handed over the deposit. Weeks later, the bank says no. Do you lose the money? It depends almost entirely on what the contract you signed says. That is why it pays to read it, and negotiate it, beforehand.
What the arras are and why the type matters
The arras are the contract with which buyer and seller reserve the transaction until signing before a notary. The buyer hands over a deposit, which is later deducted from the price. The law does not set a mandatory percentage: the amount is agreed by the parties. There are three types:
- Penitential (penitenciales). The most common in home purchases. They allow either party to back out: if the buyer withdraws, they lose the deposit; if the seller withdraws, they return it doubled (article 1454 of the Spanish Civil Code, Código Civil).
- Confirmatory (confirmatorias). An advance on the price that reinforces the commitment. If one party fails to comply, the other can demand performance or termination of the contract.
- Penalty (penales). An agreed penalty for non-compliance, which does not release anyone from the obligation to perform the contract.
For them to be penitential, the contract must say so clearly: the courts interpret this type restrictively, and simply calling the money handed over a “deposit” is not enough.
If the bank refuses the mortgage, what happens to the deposit?
If the contract says nothing about financing, a refused mortgage does not release you: in practice it is treated as the buyer withdrawing and, with penitential arras, you lose the deposit.
With a clause making the purchase conditional on obtaining the mortgage, the situation changes: if the bank refuses it on the agreed terms and you can prove it, you get the deposit back.
An example with figures: a €250,000 property and a deposit of €25,000 (10%). Without a financing clause, a refused mortgage can cost you that €25,000. On the other hand, if it is the seller who backs out with penitential arras, they must pay you back €50,000.
Illustrative example with fictitious figures. What happens in each case depends on the exact wording of the contract.
The financing clause: what it should say
A generic wording such as “subject to mortgage” falls short. The clause should specify:
- The minimum financing amount you need to buy.
- The deadline for obtaining approval, with enough margin for the valuation (tasación) and the bank's assessment.
- How many lenders must refuse the application, if a number is set.
- How the refusal is proven: for example, with a written communication from the lender.
- What happens to the deposit if the mortgage does not come through: full refund and within what period.
If you are buying in Catalonia, the Catalan Civil Code regulates arras with its own rules: have the contract reviewed before signing.
The best protection: knowing in advance how much you will be lent
The clause protects you if things go wrong. Ideally, they should not go wrong. Before handing over the deposit, you should have:
- A pre-approval or feasibility study of your mortgage, based on your real income.
- Your savings properly counted: the down payment and the purchase costs. We explain it in our article on how much money you need to buy.
- A margin in case the valuation comes in low: if the property is valued below the price, the bank will lend less.
- A realistic timeline until the notary.
The most common mistakes
- Signing the estate agency's reservation without reading what happens if there is no mortgage.
- Accepting a deadline that is too short to obtain financing.
- Applying for the mortgage after signing the arras, rather than before.
- Not keeping the banks' answers in writing.
- Taking it for granted that you will get it just because you have a good salary.
The Duplo Capital advantage
Reaching the arras knowing how much you will be lent is the simplest way not to put your deposit at risk.
Frequently asked questions about arras and refused mortgages
It depends on the contract. If it does not include a clause making the purchase conditional on financing, you will usually lose the deposit. With that clause, and if you prove the refusal on the agreed terms, you can get it back.
Penitential arras allow withdrawal: the buyer loses the deposit or the seller returns it doubled. Confirmatory arras are an advance on the price: if one party fails to comply, the other can demand performance or termination of the contract.
The law does not set a percentage: it is agreed between buyer and seller. The larger the deposit, the more important it is that the contract protects you if the financing falls through.
Whatever the clause specifies. The most common is a written communication from the lender. Always keep the answers in writing.
That is why the clause should set a minimum financing amount. If it only says “subject to mortgage”, an approval for a lower amount can lead to disputes.
Before. A pre-approval tells you how much you can borrow and lets you negotiate the arras deadline with real figures.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT