Most buyers sign their mortgage with the bank where they already have an account. It is convenient, but rarely the cheapest option. Two offers for the same home can differ by tens of euros a month and thousands of euros over the life of the loan. We explain why it pays to compare, what really matters and how to do it without losing weeks.
The mortgage market has changed in 2026
The 12-month Euribor closed September 2026 at 3.247%, compared with 2.954% in August, according to the Bank of Spain. The average rate on new home mortgages stood at 3.08% in August, the highest level since January 2025 (INE, Spain's National Statistics Institute).
The Bank of Spain has also found that banks tightened some lending criteria in 2026. In a market like this, the gap between the best and the worst offer widens, and comparing stops being a detail and becomes the most profitable decision of the whole purchase.
How much you can save by comparing
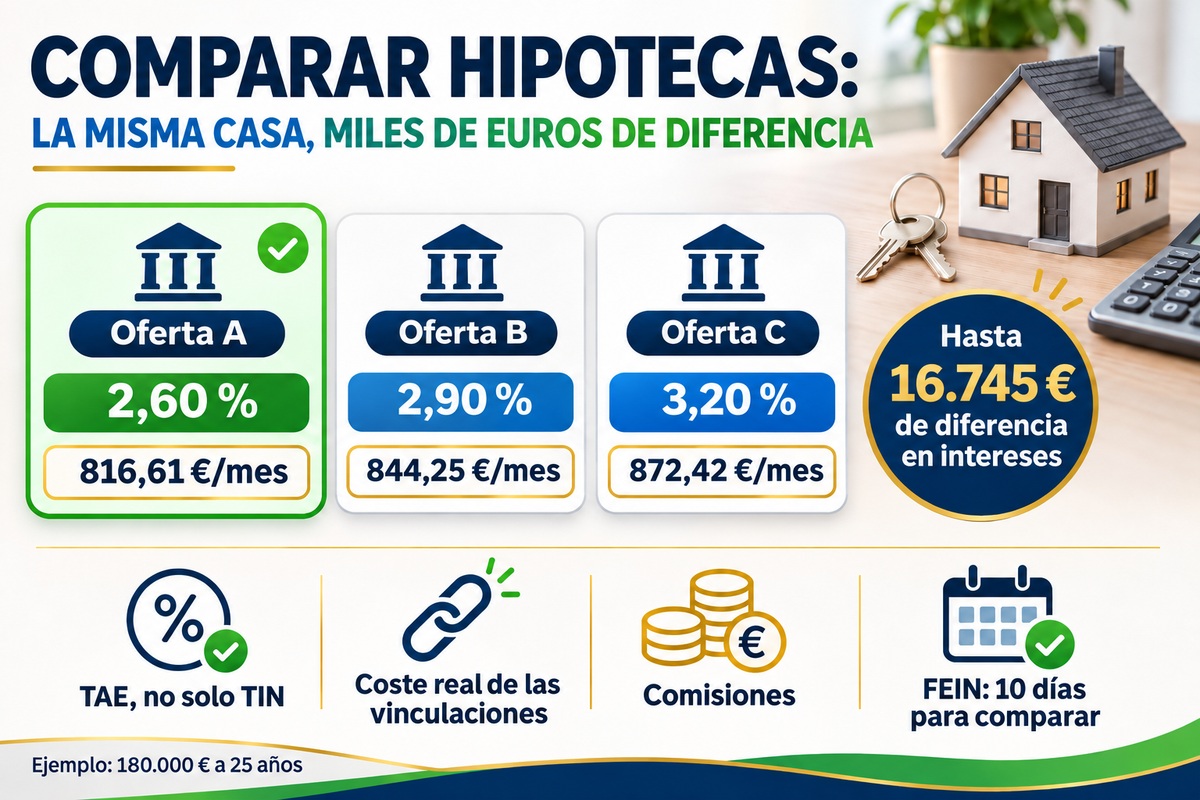
A simple example with a €180,000 mortgage over 25 years, close to the average home loan in Spain:
| Interest rate | Monthly payment | Total interest |
|---|---|---|
| 2.60% | €816.61 | €64,982 |
| 2.90% | €844.25 | €73,274 |
| 3.20% | €872.42 | €81,727 |
Illustrative example using the French amortisation system, excluding fees and insurance.
Between the first and the last offer there is a difference of €55.82 a month and €16,745 in interest over the life of the loan. Just by choosing the right bank.
The most common mistake: comparing only the interest rate
The rate shown in the advertising is almost never the one you will pay. To compare properly, you need to look at several elements at once:
- TIN — The nominal interest rate of the loan. It is used to calculate the monthly payment, but it does not include fees or insurance.
- TAE — The annual percentage rate: it includes the TIN, fees and the cost of some mandatory products. It is the best benchmark for comparing two offers.
- Linked products — Salary direct deposit, life and home insurance, cards or pension plans that the bank asks for in exchange for a lower rate.
- Fees — Arrangement, full or partial early repayment and change of rate type.
- Term and rate type — Fixed, variable or mixed: the same monthly payment can hide a very different risk.
Linked products: the hidden cost
Many mortgages advertise a very low “discounted” rate. To get it, you have to take out products that also cost money every year. The right question is not how much the rate goes down, but whether the interest savings exceed what you pay for those products.
Following the example above: going from 3.20% to 2.60% saves about €670 a year in payments. If the required insurance and products cost €700 a year, the discount ends up costing you money.
Remember too that Spain's Law 5/2019 prohibits tying practices: if the bank requires insurance, it must accept a policy from another insurer with equivalent cover, without charging you to review it and without worsening the loan conditions.
The FEIN: your tool for comparing
When the bank approves your application, it gives you the FEIN (European Standardised Information Sheet). It is a binding offer and has the same format at every bank, designed precisely so that you can compare.
The law requires at least 10 calendar days between receiving the FEIN and signing before the notary. Use them: this is the moment to put the offers side by side and negotiate.
- Total amount payable — What you will end up paying back to the bank. It is the figure that best sums up the real cost.
- Linked products — What you have to take out, for how long and what happens if you cancel them.
- Fees — Especially for early repayment or changing the rate type.
Compare, but without multiplying applications
Comparing well does not mean going from bank to bank handing over your documents. Each application takes time, and repeating the same file at many branches does not improve your profile. The effective approach is to prepare a solid file once and submit it to the lenders that suit your case.
The Duplo Capital advantage
At Duplo Capital we prepare your file once and submit it to several lenders at the same time. We compare the offers by their real cost — TAE, linked products and fees — and negotiate on your behalf until signing. All you have to do is choose the best one.
Frequently asked questions about comparing mortgages
By TAE, because it includes interest, fees and the cost of certain mandatory products. Even so, always check the total amount payable and the real cost of the linked products in the FEIN.
Ideally, you should have at least three comparable offers for the same transaction. That way you can see what is normal in the market and you have arguments to negotiate.
Bank enquiries are recorded, and piling up applications without any order can give an impression of urgency. It is better to submit a complete, well-prepared file to the lenders that suit your profile.
Only if the interest savings exceed the cost of the products you are required to take out. Ask the bank for the monthly payment with and without the discount and add up what you will pay each year for insurance, cards or other products.
Yes. If the bank requires insurance, it must accept a policy from another insurer with equivalent cover, without charging you to review it and without worsening the loan conditions (article 17 of Spain's Law 5/2019).
At least 10 calendar days between receiving the FEIN and signing before the notary. The FEIN is a binding offer: during that period the bank cannot change the conditions.
Want to know which mortgage is best for you?
We help you compare offers from several banks and give you an answer in under 48 hours.
REQUEST MY FREE ASSESSMENT