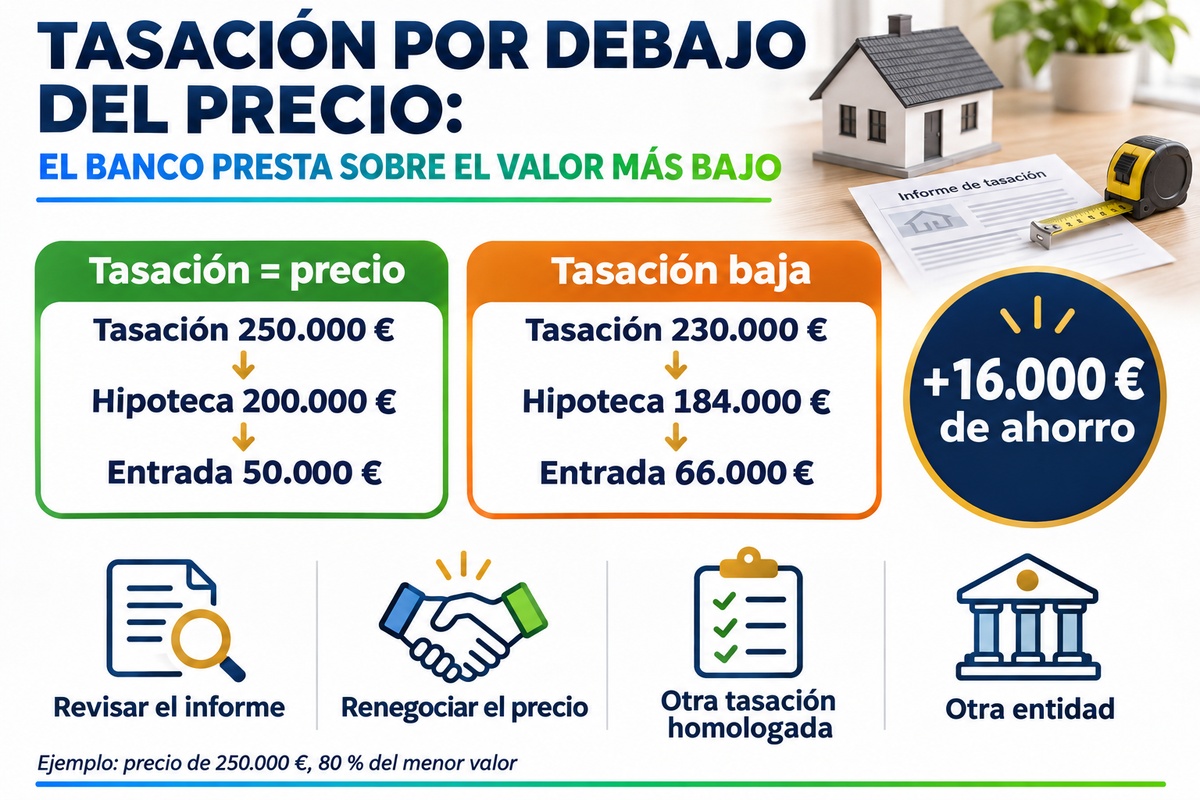
You have agreed a price, signed the deposit contract (arras) and the valuation report (tasación) arrives: the property is worth less than you are going to pay. It is not that unusual, and in many cases it can be solved. But first you need to understand what it means for your mortgage.
Why a low valuation reduces your mortgage
The bank calculates the financing on the lower of two values: the purchase price or the valuation. If the valuation comes in lower, the percentage it finances is applied to a smaller figure, and the difference comes out of your pocket.
A low valuation does not always mean you are overpaying: it may reflect a lack of recent comparable sales in the area or prices that have risen very quickly.
Example: a valuation €20,000 lower means €16,000 more in savings
| Item | Valuation equal to price | Valuation below price |
|---|---|---|
| Purchase price | €250,000 | €250,000 |
| Valuation | €250,000 | €230,000 |
| Mortgage (80% of the lower value) | €200,000 | €184,000 |
| Down payment you put in | €50,000 | €66,000 |
| Difference | — | +€16,000 |
Illustrative example with fictitious figures. Purchase taxes and costs must be added to the down payment.
Five options when the valuation comes in low
- Review the report. Check the floor area, the condition and the comparable properties. If you paid for the valuation, you are entitled to a copy.
- Renegotiate the price with the seller. The valuation is an objective argument for asking for a reduction.
- Provide another valuation. You can commission it from a valuation company approved by the Bank of Spain, and the bank must accept it while it is valid: the report expires after six months. Bear in mind, though, that a second valuation will not necessarily come in higher.
- Put in more savings, if the difference is manageable.
- Look for another lender. Some finance a higher percentage for solid profiles, and the Aval ICO can help you with your first home if you meet its requirements.
If you have already signed the arras
This is the most delicate moment: the deposit has been paid and the clock is ticking. Check what your contract says about financing: if the purchase is conditional on obtaining a minimum mortgage amount, a low valuation may trigger that clause. We explain it in our article on arras and refused mortgages.
How to get ahead of it
- Run the numbers with cautious scenarios before signing the arras: what would happen if the property were valued 5%, 10% or 15% below the price?
- Look at actual sale prices in the area, not just at listings.
- Order the valuation early: it usually takes 5 to 10 working days, and it gives you leeway within the arras deadline.
- Choose the valuer yourself: since Law 5/2019 the buyer pays for the valuation, and you can present it to any lender.
The Duplo Capital advantage
A low valuation does not have to kill the purchase if you act quickly.
Frequently asked questions about a valuation below the price
On the lower of the two values. If the valuation comes in below the price, the financing percentage is applied to the valuation.
Yes. If it is carried out by a company approved by the Bank of Spain and is still valid, the bank must accept it.
Six months from the date it is issued.
The buyer, under Law 5/2019. That is why you can choose the valuer.
Yes, if you cannot cover the difference with savings or if the valuation reveals problems with the property, such as charges or planning irregularities.
Roughly between €250 and €500, depending on the property and the valuer.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT