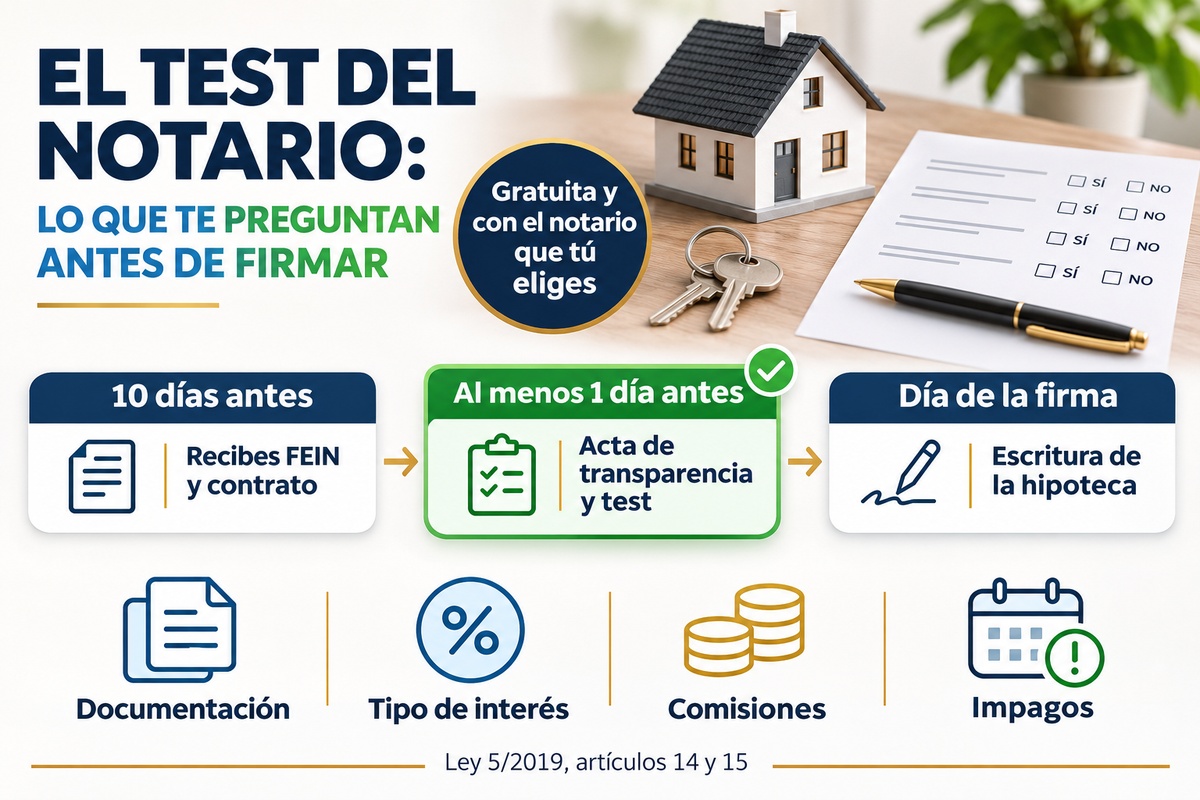
Before signing the mortgage you have a prior appointment with the notary. They will explain the contract and give you a short test of “yes” or “no” questions. It is not an exam you can fail, but it is your last chance to fully understand what you are about to sign. Here it is, question by question.
What the transparency certificate is and when it is signed
Since Spain's Law 5/2019 (Ley 5/2019), signing a mortgage on a home involves two appointments at the notary's office:
- The documents, at least 10 days before. The bank must make the binding offer (FEIN), the draft contract and the other documents available to you at least ten days in advance.
- The transparency certificate (acta de transparencia), at least one day before signing. In it, the notary checks that you received the documents on time, advises you personally and gives you the test (article 15 of Law 5/2019).
- Signing the deed, once the certificate has been done. Without it, the notary cannot authorise the mortgage.
Three important details: the certificate is free of charge, you choose the notary, and nobody from the bank attends that appointment.
It is not an exam: what the test is for
The law says the test serves to set out the documents you have been given and the information you have received. There is no mark and there are no trick questions: if an answer is “no”, the notary clarifies it with you there and then. And if a mandatory document is missing, the signing cannot go ahead until it is resolved.
That is why it is best to see it for what it is: your last opportunity to ask about anything you are unsure of, in front of a professional who does not work for the bank.
The test questions, block by block
The questionnaire may vary slightly from one notary to another, but it usually follows this order:
- 1. Pre-contractual documents. Whether you have received the FEIN, the FiAE (standardised warnings sheet), the draft contract, the costs document, the conditions of any required insurance, the notice of your right to advice from the notary and, if the rate is variable or mixed, the repayment scenarios depending on how the interest rate evolves. Also whether the bank has explained them to you.
- 2. Choice of notary. Whether you knew it was up to you to choose and whether you confirm this is the notary you chose.
- 3. Loan features. Whether you know the capital, the term, the amount and frequency of the repayments, and that each repayment includes a portion of capital and a portion of interest.
- 4. Interest rate. Whether it is fixed, variable or mixed, whether there are discounts for taking out other products and, depending on the case, what it means not to benefit from future rate cuts (fixed) or that your repayment may rise with the reference index plus the margin (variable). With a mixed-rate mortgage both apply: first a fixed period and then a variable one.
- 5. Subrogation. Whether you know you can switch banks later through a subrogation.
- 6. Early repayment. Whether there is a fee for full or partial early repayment, or for switching banks, and that it can only be charged if the bank suffers a loss that it must justify.
- 7. Fees. Whether your loan has an arrangement fee, a fee for changing the terms or a fee for claiming unpaid repayments.
- 8. Default. Whether you know that a missed payment generates default interest and that, above a certain unpaid amount, the bank can call in the whole loan.
- 9. Foreclosure. Whether you know that a missed payment can lead to the property being auctioned and that you are liable for the debt with all your assets, present and future, unless otherwise agreed.
The figures worth having clear
| Item | What the law says | Example with a €200,000 mortgage |
|---|---|---|
| Default interest | Ordinary rate + 3 points (article 25 of Law 5/2019) | With a rate of 2.90%, default interest would be 5.90% on the unpaid amount |
| Early termination, first half of the term | Arrears of at least 3% of the capital or 12 monthly repayments (article 24) | €6,000 unpaid or 12 repayments |
| Early termination, second half of the term | Arrears of at least 7% of the capital or 15 monthly repayments (article 24) | €14,000 unpaid or 15 repayments |
| Liability | With all your assets, present and future (article 1911 of the Spanish Civil Code, Código Civil) | If the auction does not cover the debt, you still owe the difference |
Illustrative example with €200,000 of capital and a rate of 2.90%. The early-termination percentages are calculated on the capital granted.
How to prepare for the appointment
- Read the FEIN calmly and compare it with the draft contract: capital, term, rate, repayment, discounts and fees must match.
- Write down your questions before you go. The notary is there to answer them.
- If your mortgage is mixed-rate, be clear on how many years the fixed period lasts, what the margin on the variable period is and which index applies.
- Review the discounts: which products you are required to take out and how much they cost per year.
- Check the dates: the ten days from when the documents were made available, and the certificate appointment at least one day before signing.
- Bring your DNI or NIE and make sure all borrowers attend.
Common mistakes
- Answering “yes” on autopilot, without having understood the question.
- Not asking for fear of looking as if you don't know: that is exactly what the appointment is for.
- Not reading the FEIN until the day of the notary appointment.
- Confusing the certificate with the signing: they are two separate appointments, and at least one day must pass between them.
The Duplo Capital advantage
Arriving at the notary knowing exactly what you are going to sign takes a lot of pressure off the final step.
Frequently asked questions about the notary test
No. It is not a knowledge exam: it serves to record the documents and information you have received. If an answer is “no”, the notary clarifies it with you.
Nothing: Law 5/2019 states that it is free of charge for the borrower.
At least one day before the mortgage deed, and after you have had the documents available for at least ten days.
Yes. The choice of notary belongs to the borrower, and the test includes a question to confirm it.
No. The certificate is done with the notary and the borrowers, without any representative of the lender.
The notary cannot consider the requirements met, and the signing cannot be authorised until the bank provides the documents as required by law.
Want to know which mortgage you can get?
Request your free analysis and we'll tell you in under 48 hours.
REQUEST MY FREE ASSESSMENT